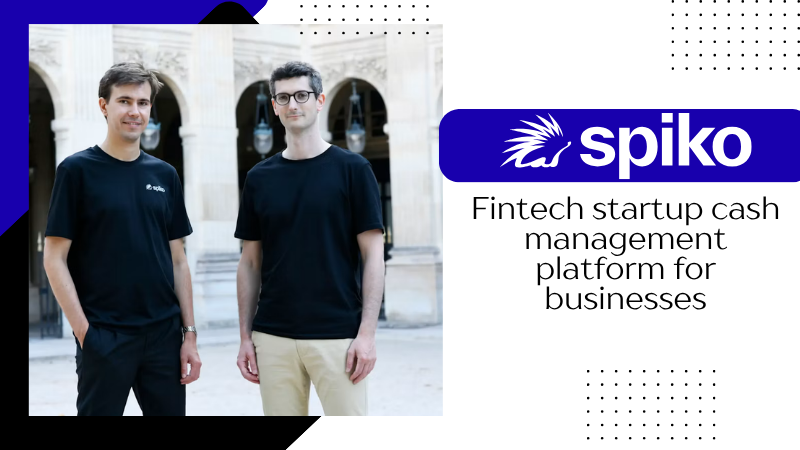
Founded in June 2023, Spiko is a French fintech startup helping businesses and individuals make better use of their cash. The company says it has already helped thousands of customers put more than €1 billion to work by offering a way to earn returns on cash that might otherwise sit in traditional bank accounts.
Spiko aims to address a common problem in business finance: companies often hold large amounts of cash in bank accounts but may not receive the interest they could earn elsewhere. Meanwhile, banks can benefit from the money deposited by their customers.
The startup wants to make cash management simpler and more transparent, allowing customers to retain greater control over their money and the returns it generates.
How Spiko Is Changing Cash Management
Spiko is building financial infrastructure designed to simplify how financial products are issued, transferred and distributed. Its first focus is helping customers earn returns on their available cash.
For businesses, managing cash is an important part of financial planning. Companies need money to pay employees, suppliers and operating expenses, but they may also have funds that are not immediately required.
Spiko aims to help customers put this money to work rather than leave it earning little or no interest. Its approach focuses on transparency, with the goal of making it easier for customers to understand how their money is invested and what returns they may receive.
The company’s central message is straightforward: customers should have a clearer understanding of the returns generated by their money.
However, investment returns are not the same as guaranteed bank interest. The risks, terms and protections depend on the financial product selected.
A Regulated Approach to Financial Services
Spiko says it operates as a MiFID investment firm licensed and supervised by French financial authorities, including the ACPR and AMF.
This regulatory framework is an important part of its business model as the company seeks to build trust among businesses and individuals looking for alternatives to traditional cash management.
Rather than focusing only on a single financial product, Spiko has broader ambitions to develop infrastructure that can support the issuance, transfer and distribution of different financial instruments.
If successful, this approach could help make certain financial services more accessible and easier to manage.
Who Founded Spiko?
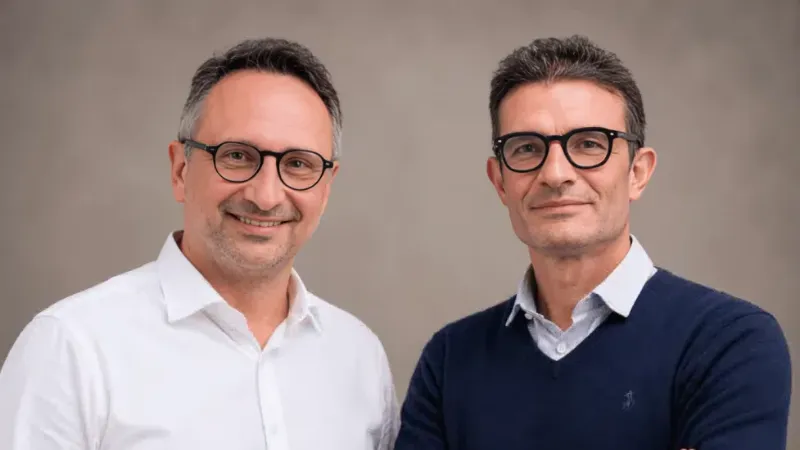
Spiko was founded by Paul-Adrien Hyppolite and Antoine Michon, who bring experience in public policy, financial regulation and technology.
Paul-Adrien Hyppolite — CEO
Hyppolite previously worked at the French Treasury, where he was responsible for financial instrument market regulation. He studied economics and finance at École normale supérieure and École Polytechnique.
Antoine Michon — COO
Michon previously worked at Palantir, where he was responsible for deployment, and later served as a ministerial adviser focused on the digital transformation of the French state. He graduated in applied mathematics from École Polytechnique.
Their backgrounds combine financial-market knowledge with experience in technology and digital transformation, supporting Spiko’s ambition to modernise how businesses manage their money.
Why Spiko Matters for Businesses
Cash management can be particularly important for small and medium-sized businesses, which need enough liquidity to cover daily expenses while making efficient use of available funds.
Traditional banking products do not always offer the flexibility or transparency that businesses want. Spiko is positioning itself as an alternative by focusing on accessible financial products and a clearer relationship between customers and the returns their money generates.
Its reported €1 billion in customer funds put to work also points to growing demand for solutions that help businesses manage their cash more efficiently. The figure represents money put to work, not necessarily revenue earned by Spiko.
What Comes Next for Spiko?
Spiko’s long-term ambition extends beyond helping customers earn returns on idle cash. The company wants to build a broader financial infrastructure that makes financial instruments easier to issue, transfer and distribute.
That ambition places it within the wider fintech movement seeking to make financial services more transparent, efficient and accessible.
Its future growth will depend on customer adoption, the products it develops, its ability to maintain regulatory compliance and how effectively it competes with established banks and other cash-management providers.
For now, Spiko is addressing a specific business problem: helping customers understand their options and potentially earn more from the cash they hold.
For startups and growing businesses, its story highlights how fintech companies can build new services around everyday financial challenges rather than trying to replace the entire banking system at once.